

Income and Security Measure Different Things
Earning well shows how much money enters your life.
Financial security shows how confidently you manage your responsibilities.
Therefore, income measures earning power, while security reflects stability, control, and peace of mind.
Why Higher Earnings May Not Feel Secure
A high income does not automatically create financial comfort.
Instead, obligations may consume much of your income and sustain financial pressure.
Additionally, uncertainty can make strong earnings feel less dependable.
When money arrives but quickly leaves, earning well may not feel reassuring.
The Role of Stability
Financial security grows when your resources consistently support your needs.
Moreover, stability helps you respond to changes without constant worry.
However, income alone cannot show whether you can manage your finances.
Your financial choices determine how effectively income supports your overall life.
The Role of Control
Feeling secure often requires control over your financial choices.
For example, clarity helps you understand what your income can support.
Likewise, deliberate decisions reduce confusion around spending and responsibilities.
As a result, control can matter as much as the amount you earn.
Your Personalized Career Strategy
Unlock your potential with tailored career consulting. Get clear, actionable steps designed for your success. Start now!
Get StartedPeace of Mind Comes From More Than Income
Earning well can expand your financial options.
Nevertheless, options do not always create emotional reassurance.
Peace of mind develops when your financial situation feels understandable and manageable.
Thus, someone can earn well while still feeling financially unsettled.
A Broader View of Financial Well-Being
Consider income one part of financial well-being rather than its complete definition.
Then, assess whether your finances provide consistency, flexibility, and confidence.
These qualities help explain why two people with similar earnings may feel differently.
Ultimately, financial security reflects your experience of money, not merely your income level.
How Everyday Cash Flow Shapes Security
Everyday cash flow reveals how money moves through a person’s finances.
It shows how required spending affects the money available for other needs.
Therefore, daily financial conditions depend on both incoming money and outgoing obligations.
Income Shows Earning Capacity
Income shows how much money a person receives.
However, income does not reveal how much money remains after necessary spending.
Regular expenses reduce the amount available for other financial needs.
Stand Out with a Resume That Gets Results
Your career is worth more than a generic template. Let us craft a resume and cover letter that showcase your unique strengths and help you secure that dream job.
Get HiredConsequently, strong earnings and effective money management can produce different daily experiences.
Regular Expenses Set the Routine
Regular expenses claim money repeatedly throughout everyday life.
These costs determine how much income remains after routine spending.
When expenses consume most income, available cash becomes limited.
As a result, even strong earnings may leave little room for change.
Essential Commitments Require Priority
Essential commitments support necessary responsibilities and therefore require priority.
They can restrict choices when they consume a large share of available income.
Managing these obligations consistently helps maintain stable financial conditions.
Accordingly, financial stability requires attention to incoming money and required outgoings.
Available Cash Creates Flexibility
Available cash represents what remains after regular expenses and essential commitments.
This remaining amount shapes everyday choices and financial breathing room.
More available cash can create greater flexibility within a person’s finances.
Conversely, limited available cash can make ordinary changes feel more difficult.
Thus, financial security reflects the space between income and required spending.
Transform Your LinkedIn for Maximum Impact
Elevate your professional brand with a LinkedIn profile that attracts recruiters, showcases your expertise, and maximizes opportunities. Stand out in your industry with a profile built for success.
Boost ProfileAssessing Everyday Financial Stability
A practical assessment considers several connected elements.
Reviewing these elements together gives a clearer view of everyday financial stability.
This approach focuses on available capacity rather than earnings alone.
- Income shows the money entering a person’s finances.
- Regular expenses show the costs that recur.
- Essential commitments show which obligations require priority.
- Available cash shows what remains for flexibility.
Building Confidence Through Financial Buffers
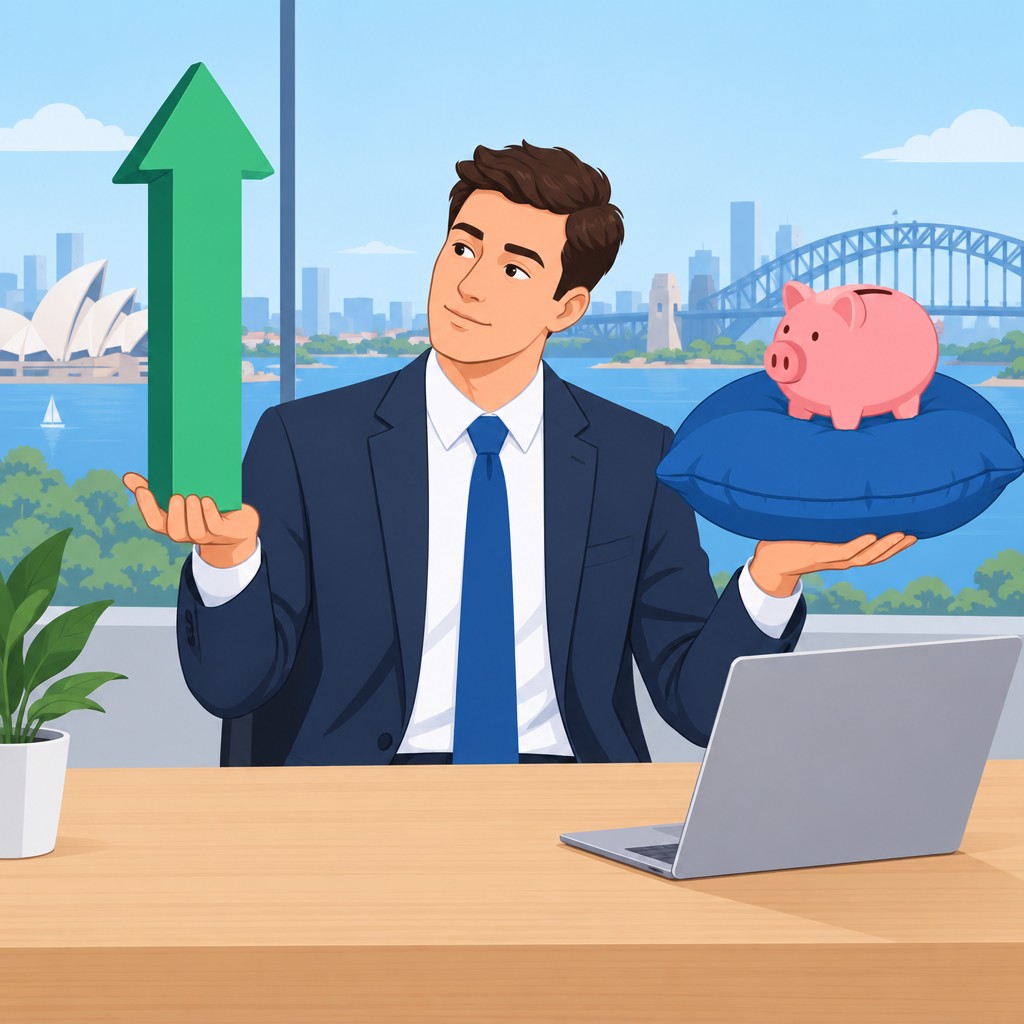
Savings can create confidence when unexpected costs arise.
They provide a financial buffer between an immediate need and available income.
As a result, one unplanned expense may feel more manageable.
Preparing for Unexpected Costs
Unexpected costs can disrupt plans when no funds remain beyond regular commitments.
However, available savings can help absorb these costs without immediate financial pressure.
This buffer also creates space to consider options before making decisions.
Therefore, saving supports more deliberate responses during uncertain moments.
Creating Flexibility When Income Changes
Income can change, even when someone earns well.
A financial buffer can help maintain flexibility during periods of reduced earnings.
Consequently, savings can reduce the urgency that follows an income change.
This flexibility may support clearer thinking while circumstances develop.
Separating Savings From Everyday Spending
Money set aside for future needs serves a different purpose than money used routinely.
Keeping that distinction clear can make financial resources easier to understand.
Additionally, separating these purposes can strengthen confidence in the available buffer.
A clear purpose helps people assess whether spending supports current needs or future resilience.
Strengthening Financial Confidence
Financial confidence grows when people know they have resources beyond immediate demands.
Still, confidence does not require certainty about every future expense.
Instead, it can come from knowing that preparation exists for changing circumstances.
Over time, consistent saving can reinforce that sense of readiness.
Ultimately, a financial buffer helps transform uncertainty into a situation that feels more manageable.
Explore Further: How Finance Workers Can Create Multiple Streams of Income
When Financial Obligations Weigh on Security
Strong earnings can still feel insufficient when debt and ongoing obligations claim much of the available income.
Required payments can reduce the freedom that earnings might otherwise provide.
This pressure can make financial security feel less certain despite a substantial income.
Debt Can Narrow Financial Flexibility
Debt creates required payments that reduce money available for other priorities.
Consequently, a person may earn well while managing limited choices during each pay period.
Regular repayments can also restrict financial decisions and reduce room for adjustments.
Furthermore, debt may keep attention focused on upcoming obligations instead of current progress.
Ongoing Commitments Shape Daily Pressure
Ongoing financial commitments continue demanding attention, even when earnings remain strong.
These obligations can include recurring payments that reduce available income.
As obligations accumulate, they can make security depend on uninterrupted earnings.
Therefore, income alone may not reassure someone when commitments leave little room for adjustment.
The Difference Between Capacity and Comfort
High earnings show financial capacity, but they do not automatically create emotional comfort.
Financial security also depends on income remaining after required payments.
When obligations consume significant earnings, financial progress may feel less visible.
Moreover, limited flexibility may feel like vulnerability despite strong earnings.
Recognizing the Pressure of Required Payments
Understanding this pressure requires examining obligations alongside earnings.
First, identify payments that remain fixed or difficult to change.
Next, consider how those payments affect available income and everyday choices.
Then, notice whether debt repayments limit responses to changing circumstances.
This perspective clarifies why financial security involves more than earnings alone.
You Might Also Like: Why Finance Professionals Question the Meaning of Job Security
How Lifestyle Inflation Changes Financial Wellbeing
Lifestyle inflation occurs when increased earnings lead to increased spending.
As spending expands, it can absorb additional income before that income improves financial wellbeing.
Therefore, earning more may change daily purchases without creating greater financial comfort.
When Higher Earnings Become Higher Spending
People may increase spending as their income grows.
They might choose more expensive options, add conveniences, or expand discretionary purchases.
However, each increase can create new expectations for maintaining that lifestyle.
Consequently, higher earnings may feel necessary rather than beneficial.
The Difference Between Choice and Pressure
Intentional spending can support enjoyment when it matches personal priorities.
Yet lifestyle inflation can make expanded spending feel automatic.
Over time, routine upgrades may become difficult to reduce.
This pressure can limit the freedom that higher earnings should provide.
Recognizing Spending Creep
Spending creep often appears through several small changes rather than one major decision.
For example, repeated upgrades can gradually reshape regular spending habits.
Because each change may seem manageable, the overall increase can remain unnoticed.
Reviewing spending patterns helps reveal whether earnings increases support meaningful priorities.
Keeping More Benefit From Higher Earnings
First, identify which spending increases genuinely improve daily life.
Next, question purchases that follow income growth without adding clear value.
Then, decide which improvements deserve continued spending.
Finally, direct remaining income toward greater flexibility instead of automatic expansion.
This approach allows higher earnings to improve choices rather than simply enlarge expenses.
You Might Also Like: How Payroll Specialists Ensure Smooth Operations in the Workplace
The Emotional Experience of Money
Money affects emotions as well as decisions.
Therefore, strong earnings may coexist with worry, uncertainty, or tension.
Emotional security depends on how money feels within daily life.
Stress Can Outlast Financial Success
Financial stress can continue even when earnings appear sufficient.
For example, uncertainty may make each financial decision feel demanding.
As a result, income alone may not create calm.
Stress can also narrow attention toward immediate concerns.
Consequently, a person may struggle to enjoy financial progress.
Uncertainty Shapes Financial Confidence
Uncertainty grows when the future feels difficult to assess.
Questions about changing circumstances can create emotional pressure.
However, financial security involves more than expecting positive results.
It also involves trusting your ability to respond when conditions change.
That trust can reduce the emotional weight of unknown outcomes.
Control Creates a Stronger Sense of Security
Control gives money a clearer personal direction.
When people understand their choices, they may feel less overwhelmed.
Additionally, control supports deliberate decisions instead of reactive responses.
It can help people connect financial actions with personal priorities.
Therefore, feeling secure often depends on agency as much as income.
Personal Meaning Influences Financial Wellbeing
People attach different meanings to money.
For some, money may represent freedom, flexibility, or reduced pressure.
For others, it may represent responsibility, protection, or independence.
These meanings shape how people evaluate their financial position.
Consequently, identical earnings can create different emotional experiences.
Recognizing Your Own Definition
Personal reflection can clarify what security means to you.
First, notice which financial situations create the strongest emotional reactions.
Next, consider whether stress comes from uncertainty, limited control, or conflicting priorities.
Then, identify the conditions that would create greater calm.
This process connects financial wellbeing with personal values.
It also separates external measures from internal experience.
Security Involves More Than Appearance
A financially successful appearance does not reveal someone’s emotional experience.
Likewise, a strong income does not automatically produce confidence.
Instead, security grows when money supports clarity, control, and personal meaning.
Ultimately, financial wellbeing reflects both circumstances and feelings.
You Might Also Like: How Corporate Treasurers Manage Financial Health in Big Enterprises
Security Is Built Through Preparation
Preparation gives people a stronger way to handle financial change.
It creates a clearer response when circumstances shift.
Additionally, preparation reduces pressure to make rushed financial decisions.
Prepare for Different Possibilities
A secure financial approach considers more than one possible future.
For example, people can review responses to changing income or unexpected responsibilities.
This process reveals weaknesses before those weaknesses create immediate pressure.
Moreover, preparation helps people identify which priorities deserve protection first.
Build Flexible Financial Habits
Financial resilience depends on habits that adjust when conditions change.
Flexible habits help people respond without abandoning every important priority.
They also support thoughtful choices when circumstances require a different approach.
Therefore, security involves systems that remain useful during stable and uncertain periods.
Strengthen Decision-Making
Preparation can make financial decisions more deliberate.
People who understand their priorities can evaluate choices with greater clarity.
They can distinguish immediate preferences from actions that support lasting stability.
Furthermore, clear priorities reduce uncertainty when several options compete for attention.
Resilience Matters Beyond Income
Resilience determines how well people handle financial disruption.
It allows people to adjust, reassess, and continue pursuing important goals.
Consequently, people may feel secure when they trust their ability to respond effectively.
Respond Instead of React
A prepared person can pause and review available choices before acting.
This pause creates space for decisions that reflect priorities rather than temporary fear.
It also helps people maintain perspective when financial circumstances change.
Review Plans Regularly
Financial preparation requires regular attention because personal circumstances can evolve.
Reviewing plans helps people notice changes that could affect their security.
It also keeps financial decisions connected to current priorities.
Furthermore, regular reviews encourage small adjustments before larger changes become necessary.
Measure Security by Capacity
Financial security does not depend on reaching one universal income level.
Instead, it reflects how well a person manages responsibilities and adapts to uncertainty.
That capacity may grow through preparation, flexibility, and consistent decision-making.
Ultimately, preparation and resilience help connect earnings with genuine confidence.
A Practical Framework for Assessing Financial Security
Assess financial security by examining more than visible earnings.
Consider the conditions that make your income dependable and useful.
This approach can clarify how money supports your decisions and priorities.
Income Reliability
First, examine how consistently your income arrives.
Then, consider how clearly you understand its future continuity.
Reliable income can support clearer decisions and steadier planning.
- Identify the income sources that support your current financial decisions.
- Assess how much control you have over maintaining those sources.
- Consider whether outside conditions affect your income.
- Notice whether uncertainty affects your daily choices or long-term planning.
Strong earnings may provide comfort, but dependable earnings support clearer decisions.
Financial Flexibility
Next, assess how easily you can adjust when circumstances change.
Financial flexibility preserves room for thoughtful responses.
It also helps you respond without disrupting essential priorities.
- Review whether you can change spending without disrupting essential priorities.
- Consider how many choices remain after meeting regular commitments.
- Evaluate whether your financial structure supports deliberate decisions.
Choice and Autonomy
Financial security should expand your choices, not merely increase your purchasing power.
Greater choice can help you pause, refuse, change direction, or pursue meaningful priorities.
However, financial pressure can limit those decisions despite strong earnings.
This distinction shows whether money creates genuine autonomy or supports a demanding routine.
Protection Against Disruption
Security also depends on how your financial life responds to interruptions.
Resilience reflects the response options available during uncertainty.
Therefore, evaluate your ability to protect important priorities when conditions change.
- Consider how your plans would change if income became less predictable.
- Assess whether essential priorities could remain protected during disruption.
- Identify which financial decisions would require immediate changes.
- Notice whether uncertainty would force choices that conflict with your priorities.
Alignment With Personal Priorities
Financial security should reflect what you want your money to accomplish.
Aligned decisions can support your values, responsibilities, and preferred direction.
A simpler financial structure may feel stronger when it supports greater alignment.
Conversely, higher earnings may not improve security when they demand unwanted choices.
Personal Security Check
Use these questions to assess your financial position regularly.
Answer each question honestly rather than judging yourself by income alone.
Your answers can reveal how your finances support daily decisions and future priorities.
- Can I explain where my money comes from and where it goes?
- Can I adjust my decisions when circumstances change?
- Can I protect my most important priorities during uncertainty?
- Can I make choices without constant financial pressure?
- Does my financial structure support the life I want?
Progress Through Financial Capacity
Finally, measure progress by the capacity your finances create.
Look for clearer choices, stronger adaptability, and better alignment with your priorities.
Also, observe whether financial decisions require less fear and fewer urgent compromises.
Over time, these signs can reveal genuine security more accurately than earnings alone.


